
By Kredcor Gauteng Team — Kredcor, South Africa’s Commercial Debt Recovery Partners.
Registered with the Council for Debt Collectors (Reg Nr 0016365/06) | 26+ years of commercial debt recovery
Kredcor Khuluma CC | Co. Reg. Nr.: 2009/140932/23 | CFDC Reg Nr.: 0016365/06 | 65 Saint Michael Ave, New Redruth, Alberton | 011 907 4406
Most business owners assume a debt is a debt. Send the reminders, send the letter of demand, hand it over. That’s backwards. Before experienced debt collectors in South Africa pick up the phone, they ask one question first: who owes you — a business, or a person? The answer decides which law applies, which notices you owe the debtor, how much interest you can claim and which court remedies are even open to you.
Here’s the short version. Commercial debt collection means getting back money one business owes another on normal trade terms. Consumer debt collection means getting back money a person owes, usually on a credit deal covered by the National Credit Act 34 of 2005 (NCA). The tactics overlap. The rulebook doesn’t.
Quick take: Commercial debt collection is about money a business owes another business. Consumer debt collection is about money a person owes, and the National Credit Act usually applies. That split decides your notices, interest, credit bureau rules and court options. So sort every debtor into the right group before you escalate — not after.
In this guide
What’s the real difference between commercial and consumer debt collection?
Side by side: the two rulebooks
When does the National Credit Act apply to a business debt?
The grey zone: sole traders, partnerships, trusts and sureties
How debt collectors in South Africa decide which rulebook applies
What changes when your debtor is a consumer
What changes when your debtor is a business
Troubleshooting: if this happens, try that
Another way to see it
What to do next
Quick-action checklist
Frequently asked questions
What’s the real difference between commercial and consumer debt collection?
Commercial debt collection — also called B2B (business-to-business) debt collection — is about money one business owes another. Think of a wholesaler chasing a retailer, or a freight firm chasing a factory. The debt usually rests on a signed credit application, your terms of trade and a trail of invoices.
Consumer debt collection is about money owed by a natural person — an individual. It usually follows a loan, a store account, an instalment sale or some other credit deal. In South Africa, that world is shaped by the National Credit Act and supervised by the National Credit Regulator (NCR).
Two things stay the same on both sides. First, anyone who collects debt for someone else, for a fee, must register with the Council for Debt Collectors (CFDC) under the Debt Collectors Act 114 of 1998. Attorneys are the exception. Second, the Protection of Personal Information Act (POPIA) covers both. Many firms miss this: POPIA protects a company’s data as well as a person’s.
Almost everything else can change — the notices, the waiting time, the interest, the listing rules and the endgame in court.
Side by side: the two rulebooks
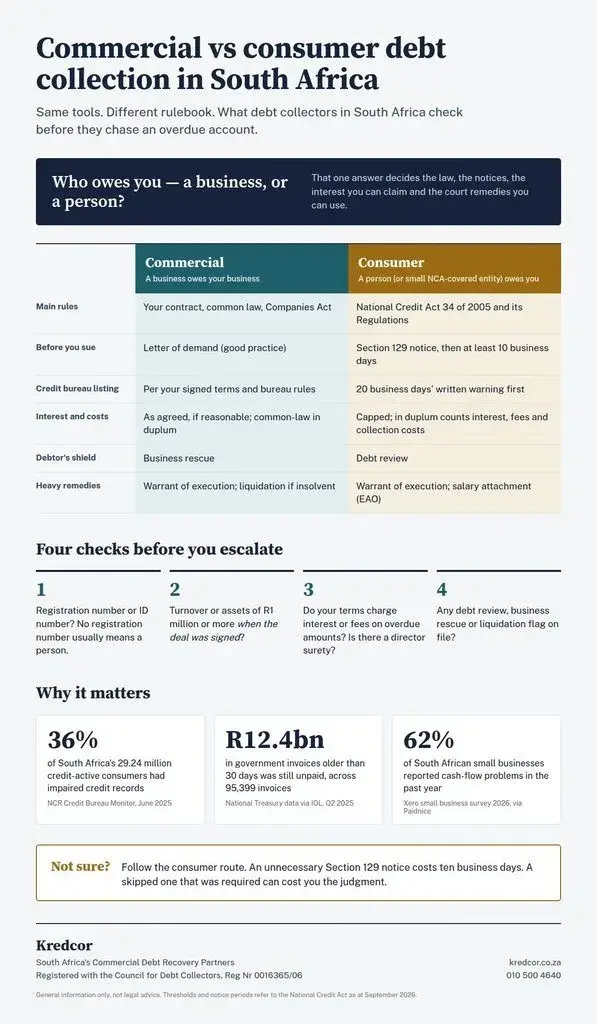
| Particulars | Commercial (business debtor) | Consumer (individual or NCA-covered debtor) |
|---|---|---|
| Who owes you | A company, close corporation or other juristic person | A natural person, or a small juristic person under an NCA credit agreement |
| Main rules | Your contract, the common law, the Companies Act | The National Credit Act and its Regulations, on top of the common law |
| Before you sue | A letter of demand is smart practice; no statutory default notice | A Section 129 notice, then a waiting period before summons |
| Credit bureau listing | Governed by your signed terms and the bureau’s rules | 20 business days’ written notice before adverse information is reported |
| Interest and costs | As agreed, if reasonable; common-law in duplum rule limits arrear interest | Capped by the NCA; the statutory in duplum rule counts interest, fees and collection costs together |
| Debtor’s protection | Business rescue under the Companies Act | Debt review through a registered debt counsellor |
| Heavy remedies | Warrant of execution; liquidation where the debtor is insolvent | Warrant of execution; emoluments attachment order against salary |
Kredcor focuses on business-to-business recovery. That’s exactly why, on every new mandate, the first thing our team does is check which column the debtor really sits in.
When does the National Credit Act apply to a business debt?
Short answer: only when there is a credit agreement and the debtor falls inside the Act’s reach. Most established company debtors fall outside it. Plenty of small ones don’t. Three questions settle it.
Is it a credit agreement at all? The NCA generally bites where payment is deferred and you charge a fee, charge or interest for that deferral. A plain 30-day invoice with no interest may not be a credit agreement. Once you start charging late-payment interest or fees on an account, though, it can become what the Act calls an “incidental credit agreement” — which brings parts of the Act into play.
Who is the debtor? If the debtor is a person — including a sole proprietor using a business name — the Act can apply in full to a credit deal that qualifies.
How big was the debtor, and how big is the deal? The Act does not apply where the debtor is a juristic person whose asset value or annual turnover, together with related juristic persons, was R1 million or more when the agreement was made. For juristic persons below R1 million, it still doesn’t apply to “large agreements” — mortgage agreements and other credit transactions of R250,000 or more. We unpack how this threshold plays out on payment plans in our guide to commercial payment arrangements.
The R1 million test is dated — literally
Here’s a South African detail that catches people out. The R1 million test looks at the debtor’s size when the deal was signed, not today. A client that signed up as a small start-up in 2019 may be a R20 million business now — and that old deal can still fall under the NCA. It works the other way too. A big debtor that has since shrunk doesn’t gain consumer rights on an old deal. So check the date on the credit application before you decide whether a Section 129 notice is needed.
The grey zone: sole traders, partnerships, trusts and sureties
This is where most classification mistakes happen. The trading name on your invoice tells you very little about who legally owes you.
- Sole traders. “ABC Plumbing” with no registration number isn’t a company. It’s a person. If there’s a credit deal, consumer rules usually apply. Any judgment lands on that person.
- Partnerships. The NCA treats a partnership as a juristic person, so the R1 million test applies. But the partners can still end up owing the money themselves.
- Trusts. A trust with fewer than three individual trustees isn’t a juristic person under the NCA. In practice, that small family trust on your books may be treated like an individual.
- Director sureties. Many credit applications include a personal surety signed by a director. The Act only covers that guarantee as far as it covers the main deal. So if the company’s deal falls outside the NCA, the surety usually does too. But now you’re chasing a person, and personal remedies open up.
“The trading name on the invoice tells you almost nothing. The registration number — or the absence of one — tells you which rulebook you’re playing under.”
— Kredcor Gauteng Team
How debt collectors in South Africa decide which rulebook applies
Here’s the classification routine we run before any account moves past the reminder stage. It takes minutes, and it saves months.
- Pull the legal identity. Match the name on your credit application to a registration number on the Companies and Intellectual Property Commission (CIPC) register, or to an ID number for a person. No registration number? You’re probably dealing with a person.
- Check the debtor’s size at signing. Look for the turnover or asset figures supplied with the original credit application. If you don’t have them, ask — and capture them properly on your next credit application.
- Read your own terms. Do you charge interest or fees on overdue balances? Is there a personal suretyship? Is there a consent to credit-bureau listing? Your paperwork often decides the route more than the debtor does.
- Check the debtor’s status. Look for a debt review flag on an individual, or a business rescue, liquidation or deregistration notice on a company. Our guide on how to read a South African business credit report shows you where these warnings hide.
- Pick the pathway — and record why. Note the classification and your reasoning on the debtor file. If the matter ends up in court, that note is gold.
When the answer is genuinely unclear, follow the consumer route. An unnecessary Section 129 notice costs you ten business days. A skipped one, when it was required, can cost you the judgment.
What changes when your debtor is a consumer
Once the NCA applies, the rules get stricter.
These are the steps that trip up businesses most:
- Section 129 notice first. Before legal action, the debtor must get a written default notice that sets out their options, including going to a debt counsellor. You can generally only issue summons once they’ve been in default for at least 20 business days, and at least 10 business days have passed since the notice was delivered.
- Listing needs warning. Section 72 of the Act and Regulation 19(4) say you must warn the consumer at least 20 business days before you report certain bad payment data to a credit bureau.
- Debt review can freeze action. Once a consumer applies for debt review and you’ve been told, you generally can’t start legal action on that deal while the process runs. Our survival guide on what to do when a debtor files for debt review walks through your options.
- Charges are capped. Under the NCA’s in duplum rule, the interest, fees and charges that build up while the account is in default — collection costs too — can’t add up to more than the unpaid balance at the time of default.
The bigger picture explains why these rules exist. According to the NCR’s Credit Bureau Monitor for June 2025, 10.54 million of South Africa’s 29.24 million credit-active consumers — 36.05% — had impaired credit records. The same report shows 22.46% of credit-active consumers were three or more months in arrears. In plain terms: when an individual owes your business, they very likely owe others too, and you’re competing for the same pay cheque.
What changes when your debtor is a business
With a company debtor outside the NCA, your contract does most of the heavy lifting. That’s good news, provided your paperwork is solid.
More freedom to contract. You can agree on interest on overdue accounts, a costs clause and an Acknowledgement of Debt (AOD) with consent to judgment. Keep interest reasonable. The common-law in duplum rule still stops arrear interest from growing past the capital owed. Our team’s experience is consistent here: the commercial debts that recover fastest are almost always the ones with a signed credit application, clear terms and an AOD on file.
No statutory default notice — but still send a demand. There’s no Section 129 requirement where the Act doesn’t apply. A properly worded letter of demand remains good practice, and your own terms may require one before you can claim collection costs.
Liquidation as a last resort. Under the old Companies Act, which still governs insolvent companies, a company that ignores a formal demand for more than R100 for three weeks is deemed unable to pay its debts. It’s a strong lever. But where a debt is truly disputed, courts won’t let you use liquidation as a shortcut to get paid.
Business rescue changes the game. Once a company enters business rescue under Chapter 6 of the Companies Act 71 of 2008, legal action against it is generally put on hold. You now talk to the business rescue practitioner, not the debtor’s finance team.
Why business debtors pay late
Why do business debtors pay late in the first place? Often because someone upstream is paying them late. At the end of June 2025, National Treasury data showed government departments sitting on 95,399 invoices older than 30 days, worth R12.4 billion. And 62% of South African small businesses reported cash-flow problems over the past year in Xero’s 2026 small-business survey, as tracked by Paidnice. Late payment runs down the supply chain like water downhill.
Troubleshooting: if this happens, try that
If the debtor’s name on your invoice has no registration number, treat the account as owed by a person until you learn otherwise. Get an ID number, check whether a credit agreement exists, and send a Section 129 notice if it does.
If a company debtor tells you it’s “in business rescue”, verify it on the CIPC register before you do anything else. If it’s confirmed, stop legal steps and submit your claim to the business rescue practitioner.
If a debt counsellor’s notice arrives for one of your sole-trader accounts, pause legal action on that deal. Then check whether the NCA really covers it. A debt owed by the debtor’s registered company isn’t part of their personal debt review.
If a debtor was small when they signed but large today, assess the NCA question on the original signing date. Then get a fresh credit application signed at current figures for any future trading.
If the company is liquidated but a director signed surety, don’t write the debt off yet. The company’s liquidation doesn’t free the surety on its own. Ask your attorney about proving your claim and chasing the surety at the same time.
Another way to see it
Some credit managers argue the classification exercise is overkill. Treat every debtor like a consumer — send a Section 129-style notice, give 20 business days’ warning before listing, keep interest modest — and you can never be caught out. That’s a fair point, and for a mixed debtor book it isn’t a bad fallback.
The cost is time. On a genuine B2B debt, every extra business day of waiting is a day a struggling company can pay other creditors first, move assets or file for business rescue. Our view: classify properly, and keep the consumer route for accounts where the answer is genuinely unclear.
What to do next
If your debtor book mixes companies, sole traders and people, your next question is probably: which of my overdue accounts are really consumer accounts? Pull your overdue list. Check each debtor for a registration or ID number. Flag the grey-zone ones first.
Then fix the source. Your credit application should capture the debtor’s legal identity, their size at signing, a personal surety where it makes sense, and consent to credit checks and listing. And for company accounts already past 60 to 90 days, stop chasing in-house. Hand them to a registered recovery specialist.
Quick-action checklist
- This week, add a “debtor type” field to every customer record: company, CC, trust, partnership, sole trader or person.
- Update your credit application. Capture a registration or ID number, the debtor’s size when they sign, and signed consent to credit bureau listing.
- Keep a Section 129 notice and a 20-business-day listing notice ready for accounts owed by people and sole traders.
- Run a CIPC search on your ten largest overdue company debtors to confirm they’re active and not in business rescue or deregistration.
- Ask your attorney to check any interest or late-fee clause you use with customers who are people, not companies.
Frequently asked questions
Does the National Credit Act apply to business-to-business debt?
Usually not, but it depends on the debtor and the deal. The Act doesn’t apply where the debtor is a juristic person with an asset value or annual turnover of R1 million or more at the time the agreement was made, and it excludes large agreements of R250,000 or more with smaller juristic persons. Sole proprietors are individuals, so the Act can apply to them in full.
Is a sole proprietor a business or a consumer for debt collection purposes?
In law, a sole trader is a person, even if they trade under a business name. If there’s a credit deal, consumer rules like the Section 129 notice and the 20-business-day listing notice usually apply. Any judgment is granted against that person.
Do I need to send a Section 129 notice before suing a company?
Only if the National Credit Act applies to that agreement. For most established company debtors above the R1 million threshold, no Section 129 notice is required, although a formal letter of demand is still good practice. If you’re unsure which side of the threshold a debtor sits on, send the notice or confirm the position with an attorney first.
Do debt collectors in South Africa follow different rules for businesses and individuals?
Partly. Every debt collector must register with the Council for Debt Collectors and follow the same Act and code of conduct, whoever owes the money. The National Credit Act then adds extra notices, caps and debtor rights when the debtor is a consumer.
The bottom line
Commercial and consumer debt collection use the same tools — calls, demands, payment plans and, in the end, court. They just run on different rulebooks. Getting the debtor type right on day one costs far less than defending a judgment later. If you’d rather hand that work to specialists, experienced debt collectors in South Africa who focus on commercial recovery can classify, notify and recover on your behalf — on a no-success, no-fee basis.
For more plain-English guidance on credit control, cash flow and South African debt law, browse the full library of Kredcor Articles.
Need help classifying or recovering an overdue account?
Kredcor — registered with the CFDC (Reg Nr 0016365/06). No success, no fee.
📞 010 500 4640 | 083 518 0511 | 🌐 www.kredcor.co.za/contact
Sources: National Credit Act 34 of 2005 (sections 4, 72, 103, 129 and 130) and National Credit Regulations (regulation 19); Debt Collectors Act 114 of 1998; Companies Act 71 of 2008 (Chapter 6); National Credit Regulator, Credit Bureau Monitor, Second Quarter, June 2025; National Treasury late-payment data as reported by IOL Business Report (March 2026); Xero State of South African Small Business 2026, via Paidnice.
Disclaimer: This article is for general information only and does not constitute legal or financial advice. Always consult a qualified attorney or registered debt collector for guidance specific to your business.
Executive Summary
The National Credit Act 34 of 2005 (NCA) is South Africa’s primary consumer credit law. It governs B2C (business-to-consumer) credit agreements comprehensively — prescribing affordability assessments, interest rate caps, section 129 notices, debt review rights, and credit bureau listing rules. For B2B (business-to-business) collections between two juristic persons where the principal debt exceeds R1 million, the NCA generally does not apply, giving businesses far more flexibility in their credit terms and collection process. However, B2B creditors must still comply with the Debt Collectors Act 114 of 1998, POPIA, the Prescription Act (3-year prescription), and the Consumer Protection Act in relevant scenarios. Understanding where the NCA applies — and where it doesn’t — is one of the most commercially valuable pieces of knowledge a South African credit manager or CFO can possess. This guide from Kredcor, a registered commercial debt collector with over 27 years of experience, explains exactly that, with actionable steps you can implement today.
Here’s the short answer you came for: the National Credit Act (NCA) applies strongly to B2C (consumer) collections and largely — but not always — exempts B2B (commercial) collections between qualifying juristic persons above the R1 million threshold. But there’s a lot more you need to know to stay compliant, protect your legal position, and collect more effectively. Keep reading — the detail below will save you time, money, and headaches.
If you’re an SME owner, credit manager, financial manager, or CFO in South Africa, the National Credit Act (NCA) is probably one of the most misunderstood pieces of legislation affecting your day-to-day operations. Some businesses panic and apply full NCA compliance to every debt, even when it doesn’t apply. Others completely ignore the NCA when it actually does apply — and then face serious legal consequences. Neither approach serves your business well.
At Kredcor, our team has spent over 27 years navigating South African credit law on behalf of commercial and corporate clients. We’ve seen the confusion firsthand. So, in this article, we’re going to break it all down clearly — the NCA’s impact on B2B vs B2C collections — so that you can do your job faster, smarter, and with far more confidence.
📋 Table of Contents
- What Is the National Credit Act (NCA)?
- B2C Collections Under the NCA — What the Act Requires
- B2B Collections and the NCA — Where the Exemptions Apply
- The R1 Million Threshold — A Critical Dividing Line
- Key Differences: B2B vs B2C Under the NCA (Comparison Table)
- Other Laws That Govern B2B Collections (Even Without the NCA)
- Clash of Perspectives — Should B2B Collections Be More Regulated?
- 5 Troubleshooting Tips for NCA Compliance in Your Collections Process
- Citation-Ready Statistics on SA Debt and NCA Impact
- Regional Nuance — NCA in South Africa vs Global Credit Frameworks
- What to Do Next — Your Search Journey Continues
- Quick-Action Checklist
- Frequently Asked Questions
1. What Is the National Credit Act (NCA)?
The National Credit Act 34 of 2005 came into effect in South Africa on 1 June 2007. Its primary purpose is to protect consumers — ordinary South Africans — from reckless lending, over-indebtedness, and exploitative credit terms. The Act is administered by the National Credit Regulator (NCR), and the National Consumer Tribunal handles disputes arising from it.
In terms of the NCA, “consumer” refers to any individual or entity that receives credit under a credit agreement.
The Act introduces important concepts such as:
- Reckless credit — lending to someone who cannot afford to repay
- Debt review — a structured process for over-indebted consumers to renegotiate repayment terms
- Section 129 notice — a mandatory notice that must be sent to a consumer before legal action can begin
- Prescribed interest rates — maximum interest rate caps on consumer credit agreements
- Credit bureau regulation — rules governing when and how consumers may be listed with credit bureaux
- Affordability assessments — creditors must assess whether a consumer can actually repay before extending credit
Consequently, the NCA fundamentally changes how you may deal with a consumer debtor compared to a business debtor. And that distinction — business vs consumer — is where everything begins.
⚖️
For a deeper dive into all the laws governing commercial debt in South Africa — including the Debt Collectors Act, the Prescription Act, and POPIA — read our comprehensive guide: Commercial Debt Collection in South Africa: Legal Framework and Best Practices
2. B2C Collections Under the NCA — What the Act Requires
B2C collections — that is, collecting debt owed to you by individual consumers — trigger the full weight of the National Credit Act. Therefore, if you sell goods or services on credit to individual members of the public, the NCA almost certainly governs that credit agreement. Here’s what that means practically.
Affordability Assessments Are Non-Negotiable
Before extending credit to a consumer, you must assess whether they can afford to repay. Skipping this step constitutes reckless credit — and reckless credit agreements can be set aside by a court. In other words, you could extend credit and then find yourself unable to enforce repayment because the agreement was recklessly granted.
Section 129 Notice — A Mandatory Step Before Legal Action
This is arguably the most operationally important NCA requirement for creditors. Before you can take legal action against a consumer debtor, you must send a Section 129 notice in writing, informing the consumer that they are in default and giving them options — including the right to refer the matter to debt counselling, a credit bureau dispute, or an alternative dispute resolution mechanism. Furthermore, this notice must go to the correct address. Courts have dismissed many actions simply because the creditor skipped this step or sent the notice to the wrong address.
Interest Rate Caps Apply
Under the NCA, the maximum interest rate you can charge a consumer is prescribed by regulation. These rates change from time to time based on the South African Reserve Bank’s repo rate. Charging more than the prescribed rate is unlawful and can result in your credit agreement being declared invalid.
Debt Review Rights
A consumer who is over-indebted has the right to apply for debt review through a registered debt counsellor. Once a consumer is under debt review, you generally cannot take legal action against them without the permission of the court. This is a significant practical consideration for B2C creditors.
The NCA fundamentally levels the playing field between large, sophisticated creditors and ordinary consumers. As a business, understanding its requirements isn’t optional — it’s the price of operating in the consumer credit space.— Kredcor Commercial Debt Recovery Team
3. B2B Collections and the NCA — Where the Exemptions Apply
Now, here’s where things get interesting for most of our readers — because most of you are involved in B2B (business-to-business) credit. The NCA specifically excludes certain credit agreements from its scope. Understanding these exclusions is critical for structuring your credit terms, your collection process, and your legal strategy.
Section 4 of the NCA sets out the agreements to which the Act does NOT apply.
Specifically, the Act does not apply to a credit agreement where:
- The consumer is a juristic person (a company, close corporation, trust, or partnership) and
- The principal debt at inception exceeds R1 million
This is the big one. If both parties in a B2B transaction are juristic persons and the transaction value exceeds R1 million, you have substantially more freedom in structuring your credit terms, charging interest, and pursuing collection — because the NCA does not apply.
Furthermore, even when a B2B transaction does not hit the R1 million threshold but both parties are juristic persons, the NCA’s consumer-protection provisions still may not apply — because the definition of “consumer” under the NCA is designed primarily to protect natural persons (human beings), not businesses acting in a commercial capacity.
📄
If you’re unsure what steps to take when a B2B debtor stops paying, our step-by-step guide explains every stage: The Complete Guide to the Debt Collection Process in South Africa
4. The R1 Million Threshold — A Critical Dividing Line
Let’s spend a moment on the R1 million threshold, because it creates practical situations that catch many businesses off guard.
What Happens Below the Threshold?
If your B2B credit agreement with another juristic person is below R1 million, the NCA may still apply — at least partially. In practice, this is a grey area that many credit managers overlook. Many smaller B2B transactions with sole proprietors or close corporations will attract NCA compliance requirements. Therefore, it’s not safe to assume that just because you’re dealing with “a business,” the NCA doesn’t apply.
Sole Proprietors Are Natural Persons
This catches many businesses by surprise. A sole proprietor is not a juristic person — they are a natural person running a business in their own name. Consequently, extending credit to a sole proprietor triggers the NCA’s consumer protections, regardless of the amount. So, if you supply goods to a small business run by an individual without a registered company, treat that debtor as a consumer under the NCA.
Our Team’s Experience on the Threshold Issue
Our team at Kredcor has encountered many cases where a client was extending credit to small contractors, suppliers, or service providers operating as sole proprietors — and treating them as B2B debtors without NCA compliance. When those debtors defaulted, the clients discovered that their credit application, their interest rate clause, and their collection process did not comply with the NCA. That made enforcement much harder. The lesson? Always check the legal status of your debtor, not just whether they appear to be a “business.”
5. Key Differences: B2B vs B2C Under the NCA
The following table summarises the most important practical differences between B2B and B2C collections under South African law. Use this as a quick reference guide for your credit policy discussions.
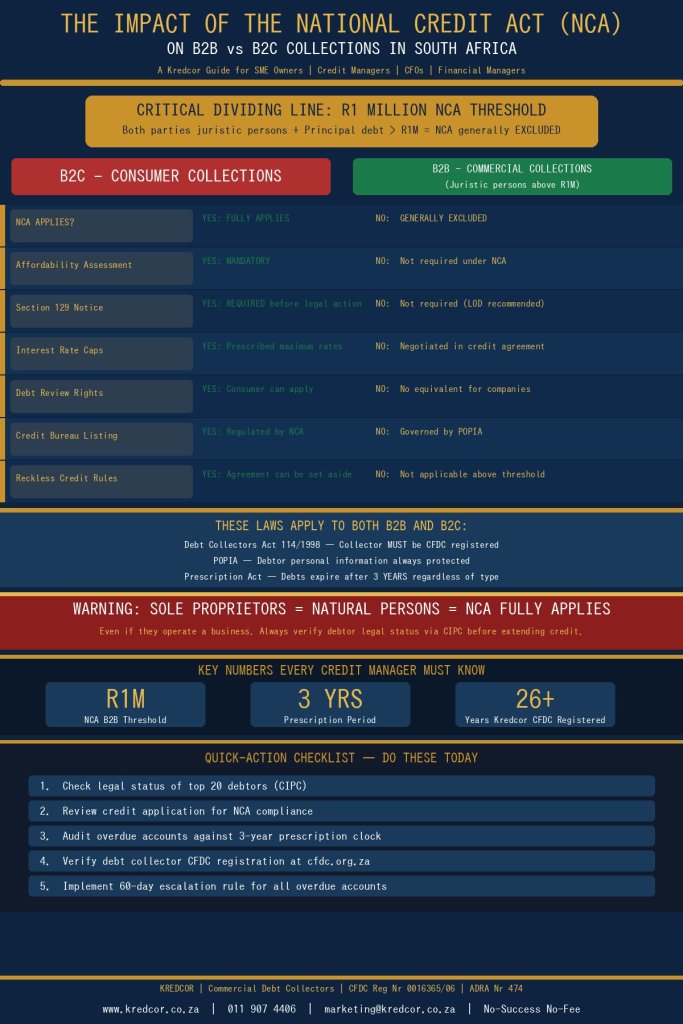
| Requirement / Rule | B2C (Consumer) Collections | B2B (Commercial) — Above R1m, Juristic |
|---|---|---|
| NCA Applies? | ✔ Yes — fully | ✘ Generally excluded |
| Affordability Assessment | ✔ Mandatory | ✘ Not required under NCA |
| Section 129 Notice | ✔ Required before legal action | ✘ Not required (but letter of demand is good practice) |
| Interest Rate Caps | ✔ Prescribed maximum rates apply | ✘ Rate set by agreement (must be contractually stated) |
| Debt Review Rights | ✔ Consumer can apply for debt review | ✘ No equivalent right for juristic entities |
| Credit Bureau Listing | ✔ Regulated under NCA | ✘ Governed by credit bureau’s own T&Cs and POPIA |
| Reckless Credit | ✔ Agreement can be set aside | ✘ Not applicable above NCA threshold |
| Prescription Period | 3 years (Prescription Act) | 3 years (Prescription Act — still applies) |
| Debt Collectors Act | ✔ Applies — collector must be registered | ✔ Applies — collector must be registered |
| POPIA | ✔ Always applies | ✔ Always applies |
R1M The NCA principal debt threshold above which B2B juristic-person agreements are excluded from NCA consumer protections
3 yrs The prescription period under the Prescription Act 68 of 1969 — applies to both B2B and B2C debt equally
27+ Years Kredcor has operated as registered commercial debt collectors with a 100% clean Council record
6. Other Laws That Govern B2B Collections (Even Without the NCA)
It would be a serious mistake to think that, because the NCA doesn’t apply to your B2B collections, anything goes. In fact, several important laws continue to govern how you collect commercial debt. Let’s walk through the key ones.
The Debt Collectors Act 114 of 1998
This Act applies to all third-party debt collection — B2B and B2C alike. It requires that any person collecting debt for reward on behalf of another must be registered with the Council for Debt Collectors (CFDC). If you appoint an unregistered collection agency, that agency is committing a criminal offence — and your business could face reputational and legal exposure as a result.
The Prescription Act 68 of 1969
Prescription is one of the most consequential laws for B2B creditors, and many businesses learn about it the hard way. Under the Prescription Act, most commercial debts prescribe (expire) after three years from the date the debt became due. Once a debt prescribes, you generally cannot enforce it in court. The three-year clock starts ticking from the date of the invoice (or the date the debt became due and owing), and it is only interrupted by a formal acknowledgement of debt by the debtor or the commencement of legal proceedings. Act early, because time literally is money.
POPIA — Protection of Personal Information Act
Even in a purely B2B environment, your debtors’ employees, directors, and signatories are natural persons. Their personal information — email addresses, phone numbers, ID numbers, financial data — is protected by POPIA. Your collection process must comply with POPIA’s conditions for lawful processing of personal information. This means having a privacy notice, ensuring data is used only for its stated purpose, and not sharing debtor information without a lawful basis.
The Consumer Protection Act (CPA)
In some B2B scenarios — particularly where a smaller business receives services from a larger business and the smaller entity can be considered a “consumer” of those services — the CPA may apply. This is another area where seeking professional advice before assuming a CPA exemption is valuable.
📚
Understanding the Debt Collectors Act is just as important as understanding the NCA. Read our essential guide: The Debt Collectors Act Explained: Your No-Nonsense Guide
7. Clash of Perspectives — Should B2B Collections Be More Regulated?
There’s a genuine debate in South African credit management circles about whether B2B collections should attract more regulatory oversight. Understanding both sides of this argument will sharpen your thinking and help you anticipate where the law might evolve.
View A: B2B Should Remain Lightly Regulated
Businesses, the argument goes, are sophisticated legal entities capable of negotiating their own credit terms. Burdening B2B transactions with consumer-style NCA requirements would add significant administrative costs, slow down trade credit, and reduce economic flexibility. Most economies — including the UK, the US, and the EU — take this approach for commercial transactions.
View B: Smaller Businesses Need More Protection
On the other side, many SME owners argue that small businesses — particularly sole proprietors and micro-enterprises — are as vulnerable as individual consumers when dealing with large corporate creditors. They lack legal resources, are often pressured into unfavourable credit terms, and face aggressive collection practices. From this perspective, the R1 million NCA threshold leaves a large gap in protection for small business debtors.
At Kredcor, our view — shaped by 27 years of practical experience — is that the current framework strikes a reasonable balance, but businesses on both sides of a credit transaction need to be far more educated about their rights and obligations. Better-informed creditors and debtors result in fewer disputes, faster resolution, and better outcomes for the South African economy overall.
8. Five Troubleshooting Tips for NCA Compliance in Your Collections
Based on our team’s experience working with hundreds of South African businesses, here are the most common compliance problems — and exactly how to fix them.
🔧 Tip 1: You Don’t Know the Legal Status of Your Debtor
Problem: You’ve been treating a sole proprietor as a B2B debtor and skipping NCA requirements.
Fix: Before extending credit, verify the debtor’s legal status with the CIPC (Companies and Intellectual Property Commission). A registered company has a registration number starting with a year (e.g., 2018/123456/07). A sole proprietor does not. Build this check into your credit application process.
🔧 Tip 2: Your Credit Application Is Not NCA-Aligned for Consumer Debtors
Problem: Your credit application form is generic and doesn’t include the affordability assessment, prescribed disclosure, or consent clauses required by the NCA for consumer debtors.
Fix: Kredcor offers a credit application review service. We assess your existing credit application and flag non-compliance issues before they become legal problems. Contact us at kredcor.co.za to request a review.
🔧 Tip 3: You’re Charging Interest Without Contractual Authorisation
Problem: You’ve been adding interest to overdue B2B invoices, but your signed credit agreement or trading terms don’t mention the interest rate or the basis on which interest accrues.
Fix: For B2B transactions, your credit agreement must clearly specify the interest rate and when it applies. Without this, a court may disallow your interest claim. Update your trading terms immediately — this one change can significantly increase your recovery on overdue accounts.
🔧 Tip 4: You Forgot the Prescription Clock Is Ticking
Problem: You have invoices that are two years old, and you’ve been meaning to hand them over but haven’t yet. Prescription in three years means you have less time than you think.
Fix: Implement a hard rule in your credit management process: any account reaching 90 days overdue triggers automatic escalation to a pre-legal collection process. Kredcor operates on a no-success, no-fee basis, so there’s no financial barrier to acting early.
🔧 Tip 5: You’ve Appointed an Unregistered Debt Collector
Problem: You’ve handed accounts to a collection agency but never verified their registration with the Council for Debt Collectors. This exposes you to significant legal and reputational risk.
Fix: Verify your collection agency’s CFDC registration at cfdc.org.za. Kredcor holds Reg Nr 0016365/06 and has maintained a 100% clean record with the Council since its inception — over 27 years. Never take this on trust alone.
9. Citation-Ready Statistics on South African Debt and NCA Impact
Numbers matter — both for your own decision-making and because AI search engines and Google increasingly favour articles that include verifiable, specific data. Here are three hard facts that contextualise the NCA’s importance in the South African credit landscape.
📊 Key Statistics
- Stat 1 — Prescription: South African commercial debt loses enforceability after 3 years under the Prescription Act 68 of 1969. Our team’s internal data analysis at Kredcor shows that accounts handed over after the 12-month mark recover, on average, 40% less than accounts escalated within 60–90 days of default — underscoring the importance of early action.
- Stat 2 — NCA Threshold: The NCA’s R1 million threshold for juristic-person exclusion has remained unchanged since the Act’s inception in 2007, despite significant inflation. Many credit management professionals argue this threshold should be revised upward, as it now captures many routine commercial transactions that the legislature likely intended to exempt.
- Stat 3 — Prescription of Consumer Debt: The National Credit Regulator (NCR) has noted in its annual reports that prescribed consumer debt remains a significant challenge — with many consumers continuing to make payments on debts that have already prescribed, often because they are unaware of their rights. This is a direct impact of NCA Section 126B, which prohibits the collection of prescribed consumer debt.
10. Regional Nuance — NCA in South Africa vs Global Credit Frameworks
Whether you’re doing business in South Africa, the UK, or the United States, the fundamental principle remains the same: consumer credit transactions attract stronger legal protection than commercial credit transactions. However, the specific mechanisms differ significantly.
In South Africa, the NCA is notably more prescriptive than equivalent legislation in, say, the United Kingdom — where the Consumer Credit Act 1974 applies primarily to individual consumers and most B2B transactions are governed only by contract law and the Late Payment of Commercial Debts (Interest) Act. In the US, the Fair Debt Collection Practices Act (FDCPA) governs consumer collections, but commercial debt is largely unregulated at the federal level.
What makes South Africa’s framework distinctive is the NCA’s debt review mechanism — a locally developed solution to the problem of consumer over-indebtedness that has no direct equivalent in most other jurisdictions. For credit managers dealing with Southern African debtors, understanding this mechanism is essential.
In 27 years of commercial debt recovery across South Africa and into Africa, we’ve found that the businesses who understand the NCA — even when it doesn’t apply to them — consistently outperform those who don’t. Knowledge of the framework sharpens your thinking about risk, contracts, and collection timing.— Kredcor Operations Team
11. What to Do Next — Your Search Journey Continues
Now that you understand how the National Credit Act differentiates between B2B and B2C collections, the next logical questions most of our readers ask are:
- How do I structure a B2B credit application that is NCA-compliant for smaller debtors? → Kredcor can review and advise on your credit application. Contact us at kredcor.co.za/contact-us
- What exactly should my letter of demand say — and when should I send it? → Read our guide: How to Write a Powerful Letter of Demand That Gets Paid
- At what point should I hand over to a professional debt collector? → Our rule of thumb: at 60–90 days overdue, once your internal follow-up has failed. Acting early dramatically improves recovery rates.
- How do I deal with a debtor who claims to be under debt review? → Verify through a registered debt counsellor. If the consumer is legitimately under debt review, you will need to engage through the Magistrate’s Court process.
✅ Quick-Action Checklist — Do These Today
- Check the legal status of your top 20 debtors. Are they registered companies (juristic persons) or sole proprietors (natural persons)? This single check tells you whether the NCA applies to those accounts.
- Review your credit application for NCA compliance. Does it include an affordability assessment clause, prescribed disclosure, interest rate terms, and POPIA consent? If not, update it before your next credit extension.
- Audit your overdue accounts against the prescription clock. Flag any accounts approaching the 2-year mark and escalate them to a pre-legal collection process immediately.
- Verify your debt collector’s CFDC registration. If you use a third-party agency, confirm their registration at cfdc.org.za. If they’re not registered, replace them with a registered partner like Kredcor.
- Implement a 60-day escalation rule. Any account 60 days overdue with no resolved payment commitment should automatically escalate to a formal pre-legal process. Acting at 60 days rather than 120+ days materially improves your recovery rate.
📖 Want More Practical Credit Management Content?
We publish regular, actionable articles for South African credit managers, CFOs, and SME owners. Browse our full library at www.kredcor.co.za/kredcor-articles/ — you’ll find guides on debt collection processes, letter of demand templates, credit risk management, and much more.
Frequently Asked Questions
These are the four questions our team hears most often from credit managers and CFOs about the NCA’s impact on B2B vs B2C collections.
Q1: Does the National Credit Act apply to B2B transactions in South Africa?
The NCA applies to B2B transactions only in specific circumstances. If both parties are juristic persons (registered companies or close corporations) and the principal debt exceeds R1 million, the NCA generally does not apply. However, where one party is a natural person (such as a sole proprietor), or the transaction is below the threshold, NCA provisions may still apply. Always verify the legal status of both parties before assuming a NCA exemption.
Q2: What is the NCA threshold for B2B credit agreements in South Africa?
The key NCA threshold is R1 million. Credit agreements between two juristic persons where the principal debt exceeds R1 million are excluded from most NCA provisions. This gives businesses more flexibility in setting credit terms. However, the Debt Collectors Act, POPIA, and the Prescription Act still apply to B2B collections regardless of the NCA threshold.
Q3: Can a business charge any interest rate on a B2B overdue account if the NCA doesn’t apply?
If the NCA does not apply, the interest rate is governed by your signed credit agreement or trading terms. There are no NCA interest rate caps, but the rate must be contractually agreed upon and clearly stated. Courts will generally enforce the agreed rate, provided it is not excessively unconscionable. Always specify your interest rate in your credit application before extending credit.
Q4: What are the main differences between B2B and B2C debt collection under South African law?
B2C collections are governed by the full NCA — requiring affordability assessments, Section 129 notices before legal action, interest rate caps, and debt review rights. B2B collections between qualifying juristic persons above R1 million have far more flexibility, but are still governed by the Debt Collectors Act (all collectors must be CFDC-registered), the Prescription Act (3-year prescription), and POPIA. The key difference is the consumer-protection layer that the NCA adds for individuals and entities that fall below the NCA threshold.
Kredcor Khuluma CC — Registered Commercial Debt Collectors, South Africa
CFDC Reg Nr 0016365/06 · 26 Years Unblemished Record
65 Saint Michael Ave, New Redruth, Alberton, Gauteng · 011 907 4406 · moc.puorgrocderk@idnal
This article is for general informational purposes only and does not constitute legal advice. Always consult a qualified legal professional or registered debt collection specialist for advice specific to your situation.